Are Australian Bank Dividends Still Attractive Amid Rising Interest Rates?
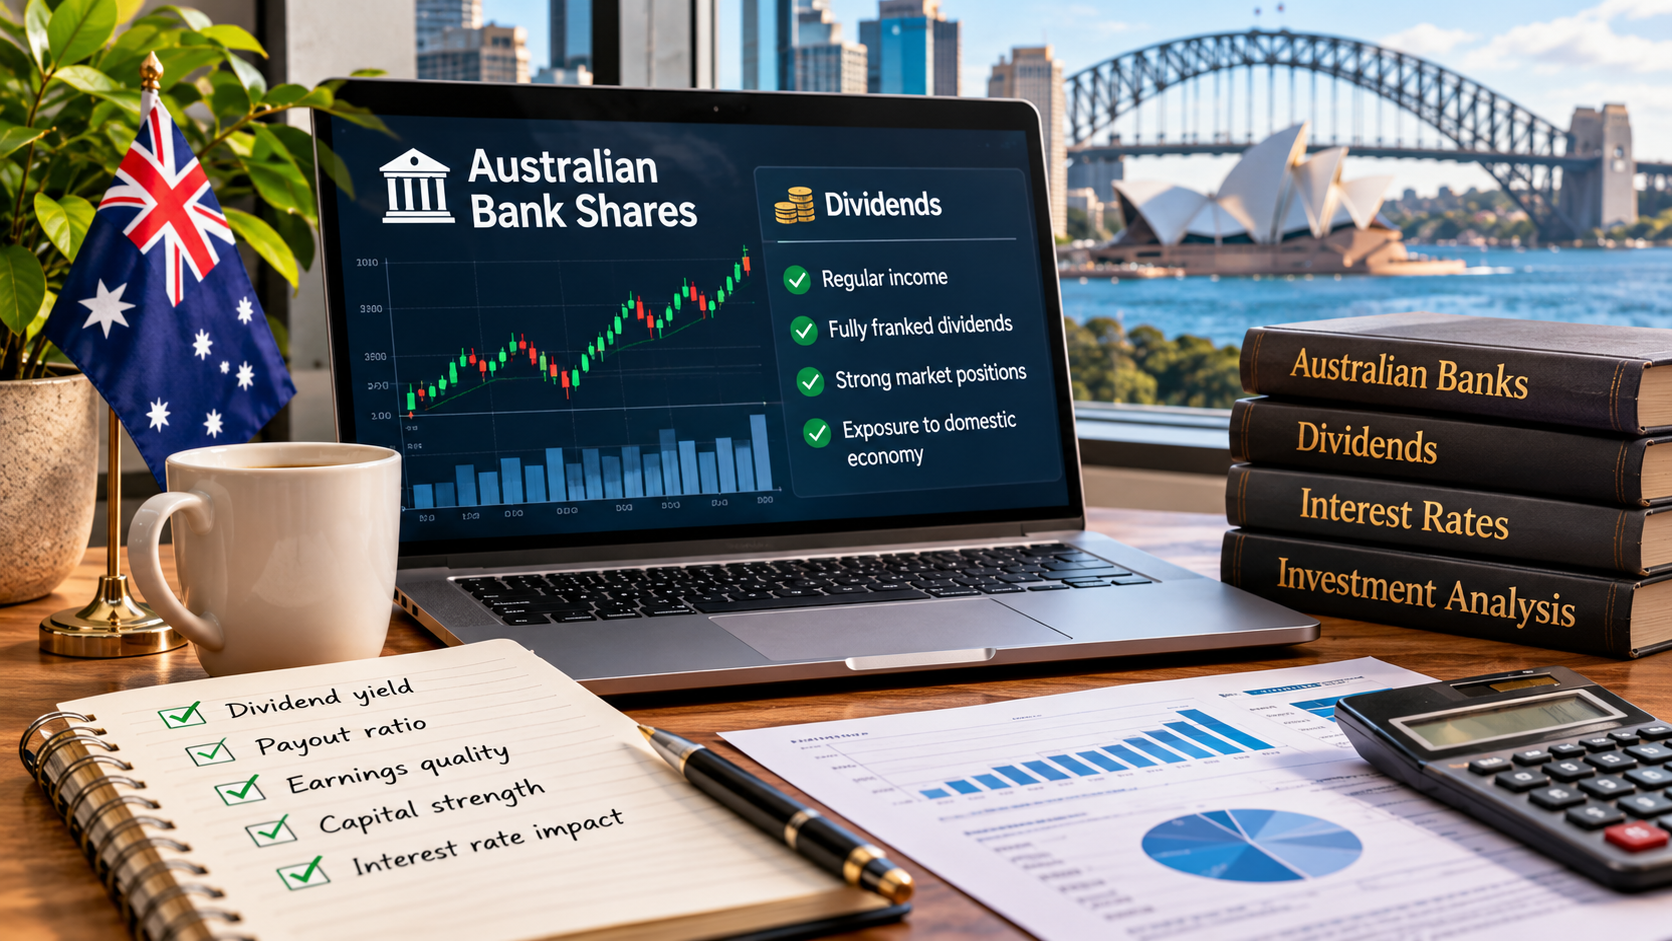
Australian bank shares have long been attractive to income-focused investors due to their established businesses, regular dividend payments and exposure to the domestic economy. But the outlook for the sector is being reshaped by changing interest rate conditions. Higher borrowing costs can also squeeze borrowers, increase loan arrears and affect credit growth, although banks can benefit from better lending margins.
The key question for investors in Australian Bank Dividends is whether the income on offer still justifies the risks. But dividend yields alone do not tell the whole story. Whether bank shares remain attractive also depends on earnings quality, payout ratios, capital strength and the general economic climate.
How Rising Interest Rates Affect Australian Banks
The Reserve Bank of Australia (RBA) lifted the cash rate to 4.85% in November 2026 after a further 25 basis point increase. Inflation remains elevated and the central bank has said it will continue to monitor economic conditions and inflation risks in making future decisions. Higher rates affect banks both on the lending income side and the funding cost side.
Higher lending rates also mean banks can make more interest on variable-rate mortgages and business loans. Net interest margins can expand if loan rates rise faster than deposit costs, boosting earnings and possibly giving companies more room to continue paying dividends. But this benefit doesn't come automatically. Banks also compete for customer deposits, and higher savings rates can raise their cost of funds.
In its November 2026 assessment of financial conditions, the RBA observed that bank funding costs had increased by some 80 basis points between January and September. Deposit rates also broadly increased in line with the cash rate, reflecting stronger competition for deposits. This means higher interest rates can increase the income from lending, but also the cost of funding.
Why Australian Bank Dividends Remain Attractive
One of the biggest attractions of Australian bank shares is their dividend history. The major banks are involved in home lending, business banking, deposits, wealth management and other financial services, which are several sources of income. Their large domestic market positions and existing customer bases can also help to underpin relatively consistent earnings through differing economic conditions.
For eligible Australian investors there is another consideration: franking credits. Fully franked dividends contain tax credits for tax already paid by the company, which can improve the after-tax value of distributions, depending on the investor's own tax position.
Recent dividend announcements indicate large distributions are continuing. Commonwealth Bank declared a fully franked final dividend of $2.70 per share for FY2026. Westpac announced total ordinary dividends of 154 cents per share for the year ended September 2026, comprising interim and final dividends. These examples show the income potential of established Australian banks, but past distributions are not a guaranty of future payments.
What Could Put Pressure on Bank Dividends?
Australian banks are finding it tough as interest rates rise, despite the attraction of income. Higher mortgage repayments can take a bite out of household disposable incomes and make it harder for some borrowers to keep up with their loan commitments. As financial pressure spreads through households and businesses, banks could see higher arrears, defaults on loans and credit impairment charges.
Slower housing activity could also impact the growth of lending. As fewer customers take out new mortgages or refinance, banks could find it hard to grow their loan books. Competition for borrowers can squeeze lending margins, limiting the benefit from higher interest rates, meanwhile.
The RBA has noted weaker housing conditions and a sharp fall in new housing lending amid tighter financial conditions. These developments are important because residential mortgages are a big part of the major banks' lending portfolios.
Another key factor is the sustainability of dividends. Banks have to balance their distributions to shareholders with the need to meet regulatory capital requirements, invest in technology and cover operating expenses and provisions for potential loan losses. If earnings weaken or credit costs increase, boards may opt to maintain dividends at current levels rather than increase.
Key Factors Investors Should Monitor
When considering Australian Bank Dividends, investors should not only look at the headline yield but also consider several indicators that can impact future distributions:
- Net interest margins: This is a measure of how well banks are doing in generating income from lending compared with the cost of their funding. Margins stable or improving can help profitability.
- Dividend payout ratios: A high payout ratio may leave less room for future increases, especially if earnings come under pressure.
- Capital adequacy: Healthy capital levels provide a buffer against unexpected losses and help banks comply with regulatory requirements.
- Bad debt provisions: Rising loan impairment charges could signal increasing pressure on borrowers and could affect profitability.
- Loan growth: In mortgage and business lending, activity can impact revenue generation and weaker demand may hold back growth.
- Franking levels: Eligible Australian investors may receive additional tax benefits from fully franked dividends, depending on their circumstances.
These measures can help investors differentiate between banks that are delivering attractive yields supported by earnings, and those where distributions may be more vulnerable.
Are Australian Bank Dividends Still Worth Considering?
Australian bank dividends could be attractive for investors looking for regular income, especially in cases where established lenders have strong capital positions, sustainable payout ratios and consistent earnings. Higher rates can support lending income, but rising deposit costs, weaker credit demand and borrower stress may offset some of these benefits.
The major banks also vary in their lending portfolios, operating performance, capital positions and dividend policies. It is more useful to compare these factors than to choose a bank based solely on its current dividend yield. Investors should also look at share valuations, as a high yield can sometimes be an indicator of a falling share price rather than improving income prospects.
Bottom line, Australian Bank Dividends could still be a part of income-focused portfolios, but their appeal will be contingent on how well each bank is able to safeguard margins, manage credit risks and sustain payouts in changing economic conditions.
Risk Considerations
Bank dividends are not guarantyd and may be reduced if earnings fall, loan defaults rise or capital requirements change. Higher interest rates can squeeze borrowers as well, while greater competition for deposits can squeeze bank margins. Share prices can rise and fall with economic conditions, property market performance and investor sentiment. Investing involves risk including the risk of loss of principal.
Disclaimer:
General Financial Product Advice and Regulatory Framework: Pristine Gaze Pty Ltd (ABN 66 680 815 678, ACN 680 815 678) operates as Corporate Authorised Representative (CAR No. 001312049) of Alpha Securities Pty Ltd (AFSL 330757), which is licensed and regulated by the Australian Securities and Investments Commission under the Corporations Act 2001 (Cth). This report contains general financial product advice only and has been prepared without consideration of your personal objectives, financial situation, specific needs, circumstances, or investment experience. The information is not tailored to individual circumstances and may not be suitable for your particular situation. Before acting on any information contained herein, you should carefully consider its appropriateness having regard to your personal objectives, financial situation, and needs, and consider seeking personal financial advice from a qualified financial adviser who can assess your individual circumstances and provide tailored recommendations.
Investment Risks and Market Warnings: All investments carry significant risk, and different investment strategies may carry varying levels of risk exposure including total loss of invested capital. The value of investments and income derived from them can fluctuate significantly due to market conditions, economic factors, company-specific events, regulatory changes, commodity price volatility, currency fluctuations, interest rate movements, and other factors beyond our control. Securities markets are subject to market risk from general economic conditions and investor sentiment, liquidity risk affecting the ability to buy or sell securities at desired prices, credit risk from issuer default or deterioration, operational risk from inadequate internal processes, sector-specific risks including industry regulatory changes, technology obsolescence, management changes, competitive pressures, supply chain disruptions, and mining-specific risks including resource estimation uncertainty, operational hazards, environmental compliance, permitting delays, commodity price cycles, geopolitical factors affecting mining operations, and exploration risks. Small-cap and speculative mining stocks carry additional risks including limited liquidity, higher volatility, dependence on key personnel, limited operating history, uncertain cash flows, and potential failure to achieve commercial production.
Information Accuracy and Limitations: While we endeavour to ensure information accuracy and reliability, we make no representations or warranties (express or implied) regarding the accuracy, reliability, completeness, timeliness, or suitability of information provided, except where liability cannot be excluded under applicable law. This report may include information from third-party sources including company announcements, regulatory filings, research reports, market data providers, financial news services, and publicly available information, which we do not independently verify and for which we assume no responsibility. Past performance, examples, historical data, or projections are not indicative of future results, and no guarantee of future returns is provided or implied. To the maximum extent permitted by law, Pristine Gaze Pty Ltd and Alpha Securities Pty Ltd, together with their respective directors, officers, employees, representatives, and related entities, exclude all liability for any errors, omissions, inaccuracies, loss or damage (including direct, indirect, consequential, or special damages) arising from reliance on information provided, investment decisions made based on this report, market losses, opportunity costs, and technical issues or system failures.
Frequently Asked Questions
Common questions about investing and market research to help guide your decisions.